
Practical Budgeting Tips to Help You Manage Your Money
9 min read
1618 words
Budgeting tips can make a real difference when you want to get more from your income and feel more confident about your financial decisions. Whether you are managing your first household budget, trying to reduce debt, or hoping to put more money toward future goals, having a plan can help you make better use of what you earn.
Creating a budget does not mean giving up the things you enjoy or putting every dollar toward bills. It means deciding how to divide your income between everyday needs, personal spending, savings, and financial priorities. With a few practical habits and a realistic approach, you can develop a budgeting routine that fits your lifestyle and helps you make steady progress toward greater financial stability.
1. Track Every Dollar You Spend
Before creating a budget, find out where your money is going. Small purchases can add up, especially when they happen regularly. Coffee on the way to work, takeout after a busy day, streaming subscriptions, and online shopping may seem inexpensive individually, but together they can take a noticeable amount from your monthly income.
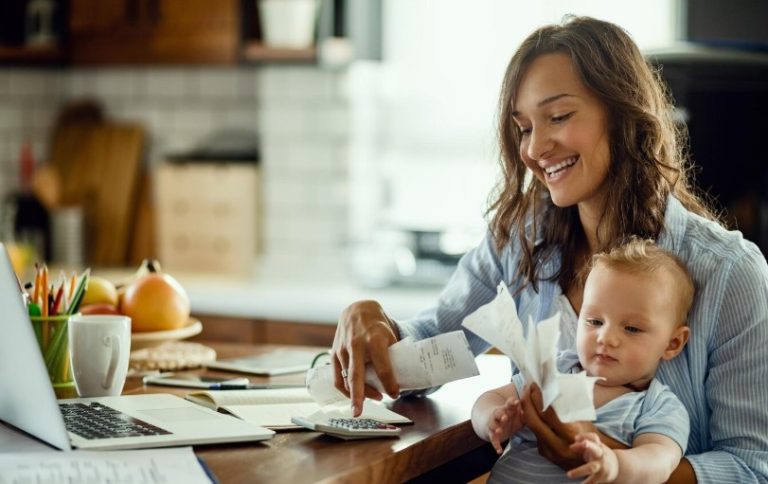
Review your bank and credit card statements for the past two or three months. Include regular bills, groceries, transportation, entertainment, and cash purchases. Record your spending in a notebook, spreadsheet, or budgeting app. Then group purchases into categories so you can see which expenses take up the largest part of your income.
The purpose is not to criticize yourself. It is to identify patterns. You may find subscriptions you no longer use or discover that convenience purchases cost more than you realized. Once you understand your habits, you can decide which expenses are worth keeping and where a change might help.
2. Create a Realistic Budget Based on Your Income

Start with your monthly take-home income, after taxes and payroll deductions. If your pay varies, use a conservative estimate based on a typical month rather than counting on your highest earnings. This can help prevent you from committing money that may not arrive.
List your regular expenses, including housing, utilities, insurance, groceries, transportation, phone service, and minimum debt payments. Remember less frequent costs too. Car registration, annual insurance premiums, school expenses, holiday spending, and routine vehicle maintenance can be difficult to manage if you have not planned for them. Estimate the yearly cost and divide it by twelve, then set aside that amount each month.
After covering these expenses, decide how much you can put toward savings, additional debt payments, and personal spending. Be realistic. A budget that leaves no room for an occasional meal out or family activity may be difficult to follow. It is better to make a plan that reflects your actual life than one that looks perfect on paper but becomes frustrating after a few weeks.
3. Prioritize Your Essential Expenses First
When money is tight, identify the expenses that protect your basic needs and keep your household running. Housing, food, utilities, transportation to work, insurance, and necessary medical costs generally come first. Knowing how much these obligations require helps you understand what is available for other purchases.
Include debt payments in your plan. Make at least the required minimum payments where possible, and consider interest rates and consequences when deciding which balances to tackle first. If you cannot afford a payment, contact the lender or service provider before the due date to ask whether payment arrangements or assistance options are available. Ignoring a bill rarely makes the situation easier.
Prioritizing essentials does not mean every other purchase is irresponsible. It means making sure important obligations are covered before spending on things that can wait. If an insurance payment is due next week, for example, postponing a nonessential purchase may help you avoid putting that bill on a credit card.
4. Build an Emergency Fund Slowly

Unexpected expenses can disrupt even a carefully planned budget. A vehicle repair, urgent dental appointment, broken appliance, or reduction in work hours can leave you short of money. Without savings, you may have to rely on credit or borrow from someone else.
An emergency fund gives you money to use when an unplanned expense occurs. A common longer-term goal is three to six months of essential living expenses, but the right amount depends on your income, household responsibilities, and circumstances. If that target feels out of reach, start smaller. Saving $10, $20, or $25 each week can gradually build a cushion.
Keep emergency savings in a separate, accessible savings account so it is less likely to become part of your everyday spending. You can increase contributions when your income allows or when another bill is paid off.
Remember that predictable expenses are not emergencies. Holidays, annual premiums, and planned vehicle maintenance should have their own savings categories. Setting money aside for these costs helps preserve your emergency fund for situations you could not reasonably plan for.
5. Use the Fifty-Thirty-Twenty Framework
The fifty-thirty-twenty framework can be a helpful starting point if you are unsure how to divide your income. It suggests using 50 percent of take-home pay for needs, 30 percent for wants, and 20 percent for savings and additional debt repayment.
Needs include housing, utilities, groceries, insurance, transportation, and essential healthcare. Wants include dining out, entertainment, hobbies, vacations, and subscriptions. The final portion can go toward an emergency fund, future goals, or paying down debt beyond the required minimum.
For someone bringing home $4,000 a month, the guideline would allocate about $2,000 to needs, $1,200 to wants, and $800 to savings and additional debt payments. These percentages are not rules that every household can follow. Housing costs may take more than half of a person’s income, or someone may need to put a larger share toward high-interest debt.
Use the framework as a guide, not a test. Adjust the percentages to fit your circumstances. The goal is to make room for essential expenses, some enjoyment, and progress toward your financial goals.
6. Automate Your Savings and Payments
Automatic transfers can make saving easier. If you wait until the end of the month to move money into savings, there may be little left. Arranging a transfer shortly after payday helps make saving part of your routine.
You do not need to begin with a large amount. A transfer of $25 or $50 each payday can help establish the habit. Increase it when your financial situation improves. If you receive a tax refund, bonus, or other additional income, consider putting some of it toward savings or debt rather than spending the entire amount.
Automatic bill payments can also help you avoid missed due dates. However, check that enough money will be in your account when payments are withdrawn. Insufficient funds can lead to overdraft fees or returned payments, particularly if your income varies. Keep track of payment dates and review your account regularly.
Automation should make money management easier, not replace paying attention. Check your statements to make sure payments are correct and look for unexpected charges or changes in recurring bills.
7. Cut Spending Without Sacrificing Quality of Life
Reducing expenses does not mean giving up everything you enjoy. Begin by looking for purchases that do not add much value to your life. You might compare grocery prices, plan meals before shopping, or use food already in your pantry. Reviewing phone, internet, and insurance plans may reveal a better rate or a service you no longer need.
Subscriptions are another place to look. If you rarely use a streaming service or membership, canceling it can free up money every month. You can also reduce convenience spending by preparing lunch at home more often or limiting takeout. These changes do not have to be all or nothing. Keeping an occasional restaurant meal or family outing in your budget can make the plan easier to maintain.
Before making a nonessential purchase, give yourself a little time to consider whether you need it and whether it fits your budget. A short waiting period can help prevent impulse spending. The aim is not to remove every pleasure from your life. It is to spend intentionally and make sure your money is going toward the things that matter most to you.
8. Review and Adjust Your Budget Regularly
A budget should change when your circumstances change. You may receive a raise, change jobs, move, take on new household responsibilities, or face higher everyday costs. A plan that worked six months ago may no longer reflect your needs.
Set aside time each month to compare your planned spending with what you actually spent. If groceries cost more than expected, consider whether prices have increased or your original estimate was too low. If you consistently have money left in one category, you may be able to direct some of it toward savings or debt repayment.
Try not to view every month that goes over budget as a failure. Unexpected costs happen, and estimates are not always accurate. Look at what changed and adjust the next month’s plan. If the same category is repeatedly over budget, revise the amount instead of setting an unrealistic target.
As your finances become more stable, you may want to consider longer-term goals such as retirement, education costs, or a major purchase. Financial planning resources from firms such as Dechtman Wealth may help you learn more about planning for the future. Any decisions should reflect your own goals, circumstances, and comfort with risk.
Make Budgeting a Habit
Your first budget does not have to be perfect. Start by tracking your spending, covering essential bills, and setting aside an amount you can manage. Review your progress and make changes as your circumstances evolve.
Small, consistent steps can make budgeting feel less overwhelming. A useful budget is not about restricting every purchase. It is about making thoughtful choices with the income you have today while preparing for the expenses and goals ahead.